Sobre Jon Iacono
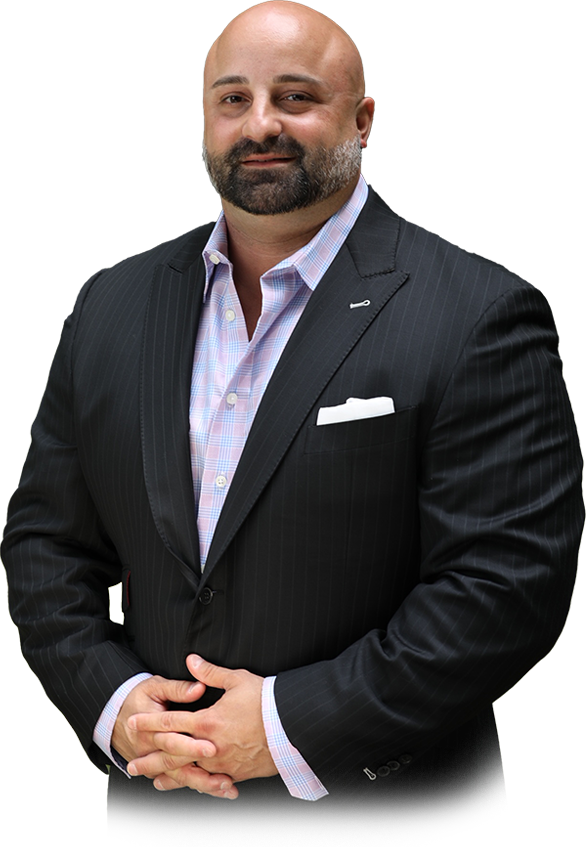
jon iacono aporta sus más de 21 años de experiencia en la industria a Advisors Mortgage Group. Jon nació en Brooklyn, Nueva York, pero vivió la mayor parte de su vida en el condado de Monmouth, Nueva Jersey. Como graduado de la Universidad de Monmouth con especialización en Administración e Informática, Jon aporta su capacitación y educación a Advisors Mortgage para ayudar a crecer y administrar el equipo de reclutamiento.
Jon trabajó junto a muchos profesionales de la industria hipotecaria y de bienes raíces anteriormente con empresas de Mortgage Intelligence como Mortgage Market Guide, Loan Tool Box, Certified, Scripts for Success, CMPS, MBS Highway, Turning Point CRM y más. Jon retribuye a su comunidad y ha sido un bombero voluntario activo para la estación Colts Neck 84 -1 desde 2004. Le gusta mantenerse activo jugando al golf, levantando pesas, boxeando, entrenando Jiu Jitsu y, lo que es más importante, pasando tiempo con sus dos hijos, Lily. y jonny jr.
El cambio de política de la Reserva Federal y su efecto en las tasas hipotecarias
septiembre 21, 2026
The Federal Reserve raised its benchmark interest rate by 0.25 percentage points, bringing the target range to 3.75%–4.00%. The Fed made the move because they feel that inflation remains elevated, while consumer spending, business investment and the labor market continue to show resilience. Higher rates are intended to slow demand and help return inflation to the Fed’s 2% goal.
Although the Fed does not directly set mortgage rates, its decisions influence the bond market and investors’ inflation expectations. When the Fed hikes rates it can be seen as deflationary since it makes borrowing money more expensive and slows down the movement of money. Bond investors’ arch enemy is inflation so a push from the Fed to fight inflation can garner more attention from investors to purchase more bonds which would help mortgage rates decrease. However, the comments following the policy change put pressure on the bond market since Fed Chair Warsh’s comments were seen as “thin” and he also mentioned inflation is still hanging around.
If inflation cools and the Fed wins the trust of the markets by continuing to fight inflation, we could see rates have a chance to improve, but if the opposite occurs rates could continue their trend and increase more. Oil is also a large factor and if we can get it to drop in price it could also assist mortgage rates to improve.
Source : Federal Reserve